Taking out a short-term loan can help when you need money for an unexpected expense. Maybe your car needs repairs. Maybe you have a medical bill you did not plan for. A short-term loan can help cover the cost when your savings are not enough.
All loans come with repayment plans, but once you have the money you need, you may start thinking about paying the loan back early.
Paying off a loan ahead of schedule can have several benefits. You may save money, free up room in your monthly budget, and reduce the amount of debt you owe. However, there are a few things you should check before making that final payment.
Early Loan Repayment Benefits
You May Save Money on Interest
One of the most compelling reasons to pay off a loan early is simple: You may pay less interest. Interest is part of the cost of borrowing money. Depending on how your loan was set up initially, paying down the balance sooner may reduce the amount of interest you pay over the life of the loan.
For example, imagine you have several months left on a loan. Then you receive extra money from a work bonus, tax refund, or another source. If you use that money to pay off the loan, you may avoid some of the interest you would have paid by keeping the loan longer.
According to Experian, saving money on interest is one possible benefit of paying off a personal loan early. However, every loan is different. Review your loan agreement or ask your lender how an early payoff would affect your total cost.
You Can Eliminate a Monthly Payment
Think about your monthly budget. How much of your money goes toward debt payments?
Once you pay off a loan, that payment is no longer required for your monthly bills. You can use that money for other needs, such as groceries, replenishing an emergency fund, or paying down credit cards. Even a small monthly payment can make a difference when money is tight.
You Can Reduce Your Total Debt
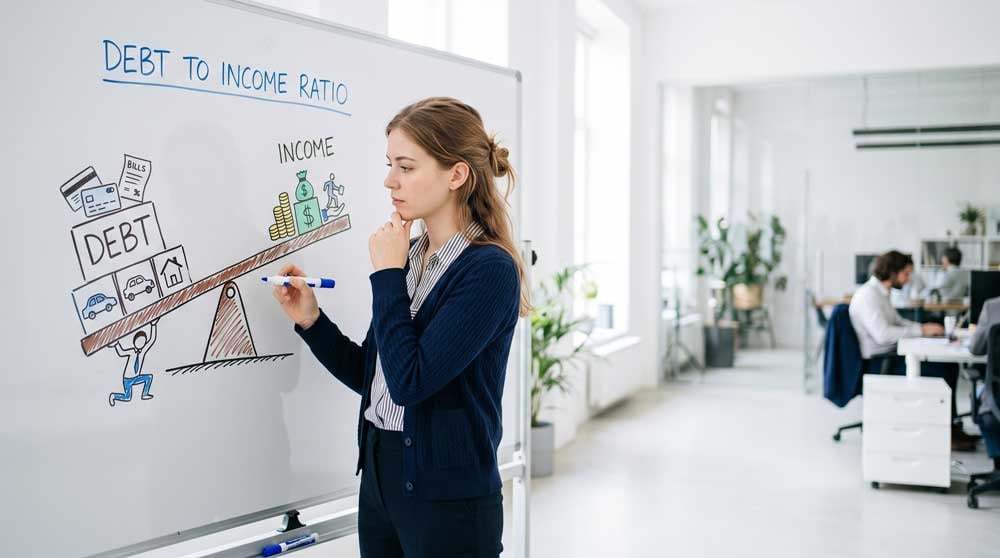
Paying off a loan means you owe less money. That may seem obvious, but lowering your debt can be an important financial goal. The fewer debts you have, the easier it may be to keep track of your bills and manage your money.
It can also lower your debt-to-income ratio, often called DTI. Your DTI compares how much you pay toward debt each month with how much money you earn. Lenders often look at this number when you apply for certain types of credit. Paying off a loan removes that monthly debt payment, which can improve your DTI.
You May Have More Money for Emergency Savings
Life does not always go as planned. Cars break down. Appliances stop working. Medical bills happen. Without savings, the next unexpected expense may mean borrowing money again.
Once your loan is paid off, consider putting some of the money you were using for loan payments into an emergency fund. Over time, even small deposits can add up. For example, if your loan payment was $150 a month, you could continue setting aside $150 after the loan is gone. After six months, you would have $900 saved.
That money could help cover the next surprise.
You May Feel Less Financial Stress
Debt can be stressful. You must remember due dates and make sure there is enough money in your account to cover each payment. When you pay off a loan, you have one less bill to worry about.
Paying off debt also gives you a clear financial win, and once one debt is gone, you can decide what goal you want to work toward next. Maybe that means starting or growing your savings. Maybe it means paying off another debt. Or maybe it simply means having more room in your monthly budget to breathe a little easier.
Does Paying Off a Loan Early Raise Your Credit Score?
There is a common belief that paying off a loan will automatically improve your credit score, but that is not always true. According to Experian's guide to paying off loans and credit scores, paying off a loan can affect credit scores differently depending on the person's overall credit history. A score could go up, go down, or change very little.
That does not mean paying off debt is a bad idea. Being debt-free can provide benefits like the ones listed above that have nothing to do with your credit score. The most important thing is to make your required payments on time while you have the loan.
Should You Use All of Your Savings to Pay Off a Loan?
This might be a question you’ve asked yourself recently. And there is no quick answer because there are so many other factors that should be considered.
Imagine you have $1,000 in savings and owe $900 on a loan. You could use almost all your savings to pay off the debt. But what happens if your car unexpectedly needs a $500 repair next week? You might have to borrow money again.
Before using your savings to pay off a loan early, think about how much money you will have left for emergencies. In some cases, keeping money in savings may be more useful than paying off a loan immediately.
You should also look at your other debts. If you have a credit card or another loan with a higher interest rate, putting extra money toward that debt could potentially save you more money in the long run.
Check for Early Payoff Fees
Before paying off any loan early, read your loan agreement in full. Some loans have a prepayment penalty or early payoff fee. This is a fee that may be charged when a borrower pays off a loan before the agreed-upon date.
Not every loan has one. The Consumer Financial Protection Bureau explains federal disclosure requirements related to whether certain loans may charge a fee for paying the principal early.
If you are unsure about your loan, contact your lender and ask: “Is there a fee or penalty for paying off my loan early, and what is my total payoff amount?” The payoff amount may be different from the balance you see online because it can include interest or other amounts owed through the payoff date. The CFPB’s explanation of payoff amounts provides more information about how payoff amounts work.
How Can You Pay Off a Loan Faster?
You do not need a large amount of extra cash to start making progress on your loan repayment. If your loan terms allow it, you may be able to:
- Pay a little more than the required payment.
- Make an extra payment when you have extra money.
- Use part of a bonus or tax refund toward your balance.
- Cut one small monthly expense and put that money toward your loan.
- Pay the remaining balance in full when you have enough savings.
Before making extra payments, ask your lender how the money will be applied. You want to understand whether the extra amount reduces your principal balance and whether there are any fees involved.
Is Paying Off a Short-Term Loan Early Worth It?
Paying off a short-term loan early may help you reduce debt, remove a payment from your budget, and potentially save money on interest. But paying off debt should be part of your larger financial plan.
Before making an early payment, ask yourself:
- Do I have enough money left for an emergency?
- Are there any early payoff fees?
- Do I have other debt that costs me more?
If paying off the loan early makes sense after answering those questions, getting rid of the debt can be a positive step toward greater financial stability.
WITHU INSIGHTS TEAM
WithU Insights is powered by a team of writers and strategists who are passionate about sharing our knowledge of the ever-changing financial landscape. Through educational articles and resources, we aim to empower you to navigate your finances and life with purpose.