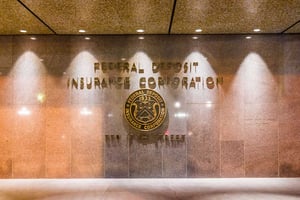
You likely have seen the logo or heard the words “Member FDIC” on a bank’s website or a commercial advertising their services. While many people know it’s a good thing, the sign of a trustworthy bank, they may not know exactly what it means.
Let’s take a look at what the FDIC is and how it helps protect you.
What Is the FDIC?
FDIC stands for the Federal Deposit Insurance Corporation. It was created by Congress in 1933, but it’s an independent agency. It’s designed to supply deposit insurance for people who use banks in the U.S.
According to the FDIC website, they also:
-
Keep the banking system stable
-
Supervise financial companies for consumer protection
-
Support public confidence in our banks
Before the FDIC, banks would often fail or file for bankruptcy because they ran out of cash. Between 1921 and 1929, 5,700 banks failed. After the stock market crash and the Great Depression, the U.S. government passed the 1933 Banking Act to create the FDIC.
What Does It Mean to be FDIC-Insured?
If you deposit money in an account at your local FDIC-insured bank, your deposit is then protected. This means that if that bank fails, you don’t lose your money. The FDIC works like any other insurance company and covers your deposit dollar-for-dollar.
There are over 4,200 FDIC-insured banks in the U.S., and the FDIC has a BankFind tool to help you find one close to you. You can search by your location or a specific bank name. It will give you detailed information about the bank, its branch locations, its official website, and more.
Note: The FDIC does not oversee credit unions. They are supervised and insured by the National Credit Union Administration.
How Does FDIC Insurance Work?
Let’s break it down with an example:
A woman named Cassie opens up a savings account at her local bank. Over the years, she saves up $20,000.
Then, suddenly, the bank fails. It closes without warning, and Cassie is cut off from her savings.
The bank, though, was FDIC-insured, so a few days after it closes, Cassie gets either a new insured savings account at a different bank with $20,000 OR a check for the $20,000 she lost.
The FDIC also goes through all the finances of the failed banks and settles any debts.
Is everything covered at an FDIC-insured bank?
No, not everything. They only cover the money you deposit in the following products:
-
Checking accounts
-
Savings accounts
-
Money market deposit accounts
-
Certificates of deposit (CDs)
-
Cashier’s checks and money orders
-
NOW accounts
The FDIC covers up to $250,000 per person, per insured bank. If you have both a single account and a joint account, they are insured separately.
The following products are NOT covered by the FDIC:
-
Stocks
-
Bonds
-
Mutual funds
-
Annuities
-
Life insurance
-
Safe deposit boxes
-
U.S. Treasury notes
-
Crypto assets
Note: You don’t have to apply for or purchase FDIC insurance. If you put your money into an FDIC-insured bank, you are covered.
Why Is FDIC Insurance Important?
The insurance provided by the FDIC serves several important functions, both for you personally and our economy in general.
Like we mentioned above, before the Great Depression and the creation of the FDIC, there was a lot of chaos in banking.
-
The Panic of 1893 and the Panic of 1896 were serious economic depressions that hit almost back-to-back.
-
The Panic of 1907 was a financial crisis where the stock market fell almost 50%.
-
Banks could be opened with very little oversight or regulation. In 1921, there were about 31,000 banks in the U.S.
The FDIC brought more stability, more security, and more oversight to banking. It serves as a safety net and has helped Americans feel more confident about entrusting their money to a bank. It has potentially prevented us from backsliding into an economic crisis as bad as the Great Depression.
On a personal level, having insurance that you don’t have to apply for or pay for makes it accessible to everyone. It’s a layer of protection that helps you weather economic downturns.
If you are saving toward your goals, an account with an FDIC-insured bank is one of the safest options available. This is especially important in an online world where your money is often just numbers on a screen.
Peace of Mind in a Rocky World
The creation of the FDIC was a turning point for banking in the U.S. We went from thousands of banks opening and failing across the country to a system that offers you more safety and more security.
You work hard for your money. Every dollar you earn goes to supporting you and your loved ones or saving for the future. You deserve to feel secure about where you’re putting it. Understanding what the FDIC is, what it covers, and what it does is an important first step so you can deposit your savings with confidence.
WITHU INSIGHTS TEAM
WithU Insights is powered by a team of writers and strategists who are passionate about sharing our knowledge of the ever-changing financial landscape. Through educational articles and resources, we aim to empower you to navigate your finances and life with purpose.