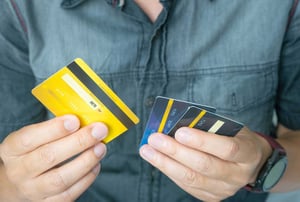
Every time we make a purchase, we have a choice to make. Do you pay for this with a credit card? Or do you use a debit card that is directly tied to the balance in your bank account? Is one option better than the other? In fact, there are pros and cons to both of them.
Defining Credit Cards vs. Debit Cards
These two little rectangles of plastic can look very similar when they’re sitting in your wallet. But they work very differently.
Credit Cards: The Pros and Cons
Credit cards are offered by banks or other financial institutions as a line of credit. They let you borrow money from the card issuer now and pay it back later. How much you can charge on it depends on the spending limit the credit card issuer sets.
-
Pros: Credit cards tend to be more secure against fraud. If your account is breached, your checking account is not at risk, and the card issuer can usually reverse fraud charges quickly. Credit cards also often offer rewards and perks in exchange for spending. And if used responsibly, they can help build your credit.
-
Cons: If you aren’t careful, credit cards can get you into debt. It can feel like “free” money and lead to overspending. But when the bill comes around the next month, you can find yourself in trouble. Credit cards also have high interest rates if you don’t pay off your bill in full. The Federal Reserve reported an average interest rate of 22.15% as of May 2026.
Debit Cards: The Pros and Cons
Debit cards are offered by any bank where you have a valid checking account. It works like a better, easier version of a written cheque. It’s tied directly to your money in that bank so you can pay for purchases. The amount you can spend is limited by your bank account balance.
Pros: There are no monthly payments and no interest charges because you aren’t borrowing. You’re just using your own money. This also means you can’t get into high-interest debt like you can with a credit card. A debit card can’t have a negative impact on your credit.
Cons: A debit card also can’t have a positive impact on your credit. Some may offer perks, but in general, credit cards have better rewards. If you aren’t keeping track of your spending, you can overdraft on your account, which means paying additional fees. There is also less fraud protection. If someone gets access to your debit card, they can drain your checking, and getting reimbursement from your bank could take time.
When to Use Both Credit and Debit Cards
It can be smart to have both a credit and a debit card, because how you use them can depend on a lot of factors. Your goals, your financial situation, and your current credit score all make a difference.
When to Use a Credit Card Instead of a Debit Card
-
If you have enough discipline. A misused credit card can do more harm than good. If you already struggle to be consistent with your bills, adding another one might be an issue.
-
If you need to build up your credit. Having a credit card and continually paying off the balance can provide a big boost to your credit score.
-
If you’re concerned with fraud protection. Credit cards can be safer for ecommerce transactions because you’re not held responsible for unauthorized purchases.
-
If you want to earn perks and rewards. This can include cash back, gift cards to cover other costs, and travel perks.
-
If you are booking a hotel stay or car rental. These businesses use credit cards to put a temporary hold on funds as a deposit. With debit cards, they charge the deposit immediately.
-
If you are getting gas or eating out. The card readers at restaurants and gas pumps are often targeted by skimmers that steal card data, and using a credit card offers more protection against fraud.
When to Use a Debit Card Instead of a Credit Card
-
If you want to avoid debt. Whether you already have debt you’re trying to dig out of or you just want to avoid getting into trouble with high interest rates, a debit card can be a better option.
-
If you tend to overspend. Debit cards are tied to your bank account balance, which means you can’t use them to spend more than you make – at least not without alerts and overdraft fees.
-
If you prefer immediacy. The impact of credit card purchases isn’t fully seen until the following month when you receive your credit card statement. You can see the effect of debit card purchases instantly as the money leaves your account.
-
If you want to avoid fees. Many credit cards come with annual fees. Debit cards, on the other hand, are something you receive for free when you open a checking account.
-
If you often need cash. Debit cards let you quickly access cash from ATMs. Credit cards offer a cash advance, but it often comes with fees.
Different Cards for Different Goals
Unless you have chronic or addictive overspending issues, it’s often good to have both a credit card and a debit card. Both have their benefits in different situations, and knowing the pros and cons of each can help you make educated decisions when it’s time to swipe a card.
WITHU INSIGHTS TEAM
WithU Insights is powered by a team of writers and strategists who are passionate about sharing our knowledge of the ever-changing financial landscape. Through educational articles and resources, we aim to empower you to navigate your finances and life with purpose.